Related video
Low Down Payment Loan Options
Conventional 3% down, FHA, VA and USDA at a glance.
Watch on its own pageWhat makes financing a Port Orchard home different from the rest of Kitsap County?
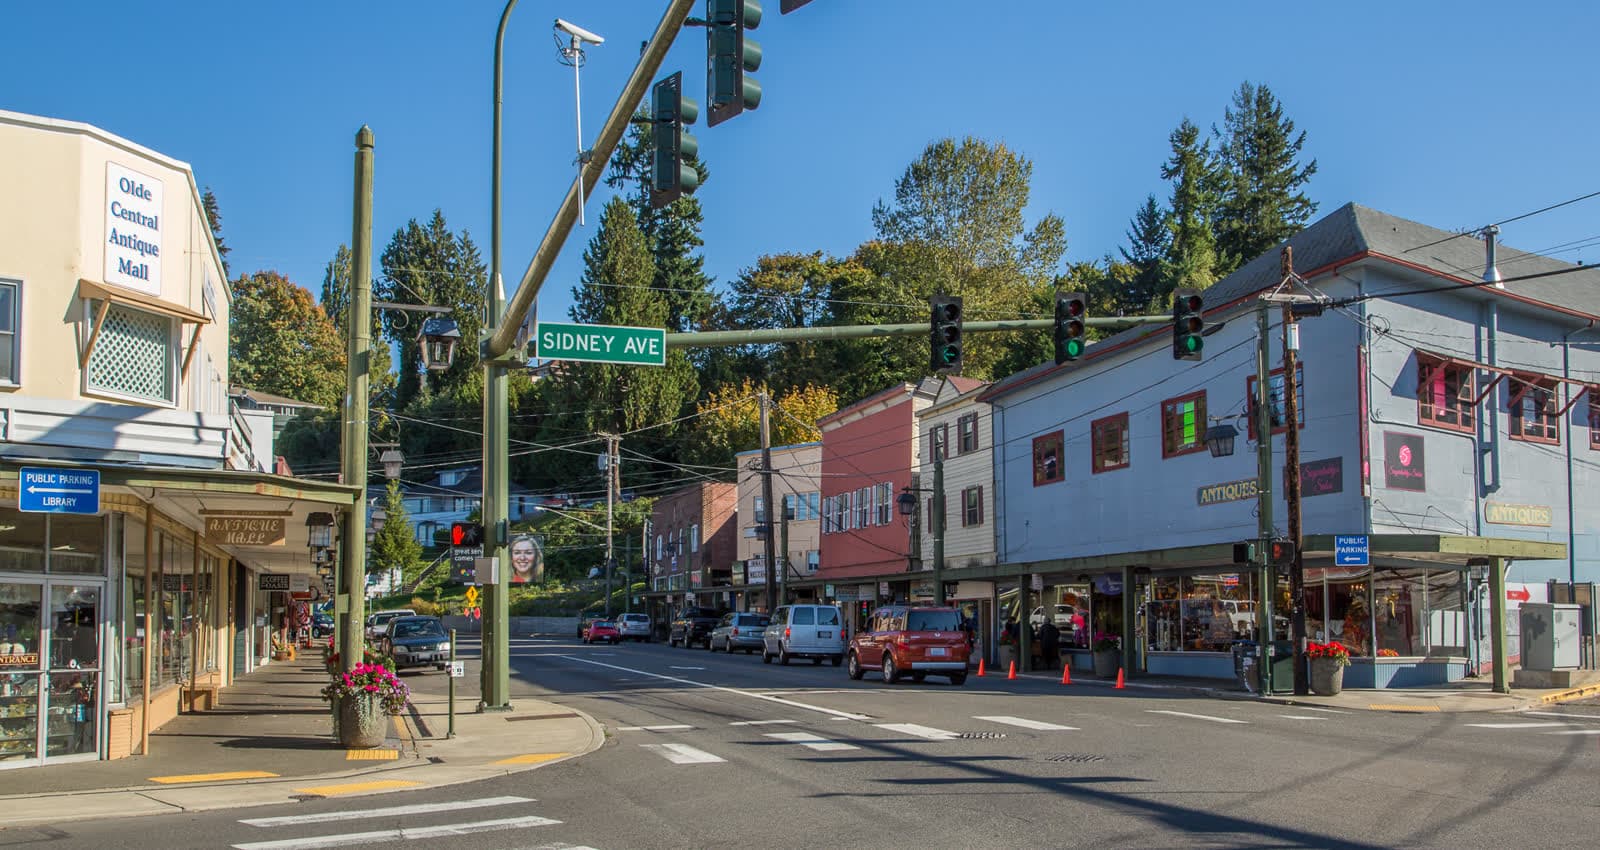
Port Orchard has a wider mix of housing than most of the county: older homes near downtown and the waterfront, large newer subdivisions, and rural parcels toward Olalla and Burley. The loan that fits depends heavily on which of those you are buying.
A few patterns show up again and again in South Kitsap:
- Newer subdivisions (planned communities with HOAs, often with golf-course or trail amenities) usually appraise cleanly and fit conventional, FHA, VA and USDA guidelines. Expect the lender to review the HOA budget and dues, and to count the dues in your debt-to-income ratio.
- Older homes near downtown, Annapolis and Manchester can be excellent value, but FHA and VA appraisals look for health and safety items: peeling paint on pre-1978 homes, missing handrails, roof condition, and working mechanical systems. Conventional appraisals are generally less condition-sensitive.
- Rural South Kitsap parcels may rely on private wells, septic systems and shared private roads. Lenders commonly ask for a well water test, a septic inspection and a recorded road maintenance agreement.
Frank's job is to match the property and your situation to the lender whose rules fit, rather than forcing one lender's rules onto every home. Banks, mortgage bankers, and credit unions offer their own loans. A mortgage broker shops the market.
I commute by ferry or work at the shipyard. Does that change how I qualify?
Not the qualifying math itself, but lenders do look at how you are paid. Shipyard shift differentials and overtime can count as income with a two-year history, and ferry commuters working for Seattle employers qualify like any other W-2 borrower.
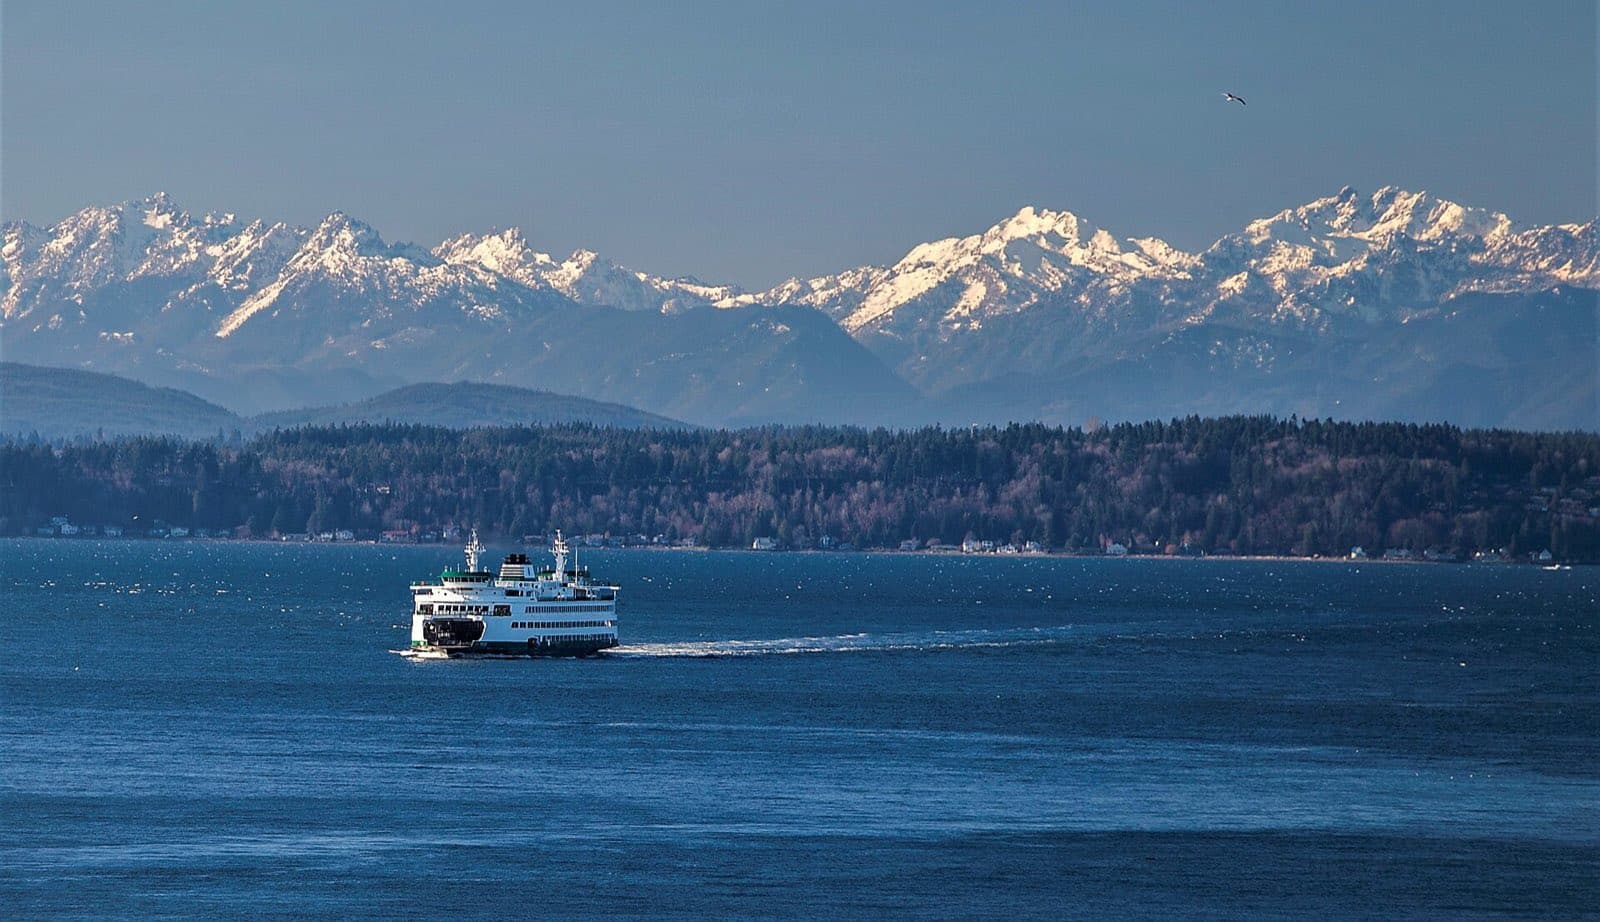
Port Orchard's two commutes shape who buys here. Kitsap Transit's foot ferry connects downtown Port Orchard to the Bremerton ferry terminal, a short walk from the Puget Sound Naval Shipyard gate. The Southworth terminal, south of Manchester, runs Washington State Ferries service to Vashon Island and Fauntleroy in West Seattle.
For shipyard and other federal employees, lenders document base pay with pay stubs and W-2s. Overtime, shift differential and night pay can be used when there is a consistent history, typically two years, and the lender is comfortable it will continue. Recent hires with a federal appointment letter can often use it to qualify before the first paycheck.
Active-duty service members commuting to Naval Base Kitsap can use their Basic Allowance for Housing (BAH) as qualifying income. BAH is not taxed, and many lenders "gross up" non-taxable income for qualifying purposes. Bring a current Leave and Earnings Statement.
Remote and hybrid workers employed in Seattle or elsewhere qualify on their W-2 income as usual. If you are self-employed, expect to document two years of tax returns; a broker can identify lenders whose self-employment rules fit how your income actually arrives.
Which low down payment options work in Port Orchard?
VA (zero down for eligible borrowers), USDA (zero down in eligible rural areas within income limits), FHA (3.5% down) and conventional loans with 3% to 5% down are all common here. Washington State Housing Finance Commission programs can add down payment assistance.
With a large military and veteran population, VA loans are a natural fit in South Kitsap. Eligible buyers with full entitlement can purchase with no down payment and no monthly mortgage insurance. Our Kitsap County VA guide covers entitlement, residual income, seller concessions and the funding fee in depth.
USDA guaranteed loans are worth checking for addresses outside the Port Orchard city limits. Eligibility depends on the specific address and on household income limits, and USDA's maps change over time. Check the exact address on the USDA eligibility map (opens in a new tab) before assuming either way.
FHA allows 3.5% down and is forgiving of thinner credit histories; it carries an upfront and an annual mortgage insurance premium. Conventional loans allow as little as 3% down for first-time buyers, with private mortgage insurance that can be removed later as equity grows.
The Washington State Housing Finance Commission (opens in a new tab) offers down payment assistance second mortgages that pair with these first loans, subject to income limits and a homebuyer education class. See our Kitsap first-time buyer guide for the details. All figures discussed before underwriting are estimates, not a commitment to lend.
The home is on septic and a private well. What will the lender require?
Expect a septic inspection, a water quality test and proof of legal access if the home is on a shared private road. FHA and VA have specific distance and water-quality rules; conventional lenders lean on the appraiser and local health requirements.
Much of South Kitsap outside the city's sewer service area is on septic. Kitsap Public Health District records septic permits and inspections, and many purchase contracts in the county call for a septic inspection as a matter of course. The appraiser will note whether the home is on public water and sewer or on a well and septic.
For FHA and VA loans, the water must meet local health standards and there are minimum separation distances between wells and drainfields. If a shared well serves several homes, a recorded shared well agreement is required. For conventional loans, the lender generally follows the appraiser's comments and the purchase contract, but a failed septic inspection will stall any loan until it is resolved.
If the property is reached by a private road, the lender will want to see a recorded easement or road maintenance agreement showing legal, year-round access. Ask the listing agent for these documents early; they are easier to fix before you are under contract than after.
How does a refinance work for a South Kitsap homeowner?
A refinance replaces your current loan with a new one at today's terms. It makes sense when the monthly savings recoup the closing costs within the time you plan to stay, or when you need to change the loan structure, remove mortgage insurance or take cash out.
South Kitsap homeowners refinance for the usual reasons: a lower rate, a shorter term, dropping FHA mortgage insurance by moving to conventional once equity allows, consolidating a second mortgage or HELOC, or pulling cash out for a remodel or an ADU.
Veterans with an existing VA loan have the VA IRRRL streamline option, which requires no appraisal in most cases and no income re-verification, but must pass VA's net tangible benefit and 36-month recoupment tests. Our VA IRRRL guide walks through those rules, and the refinance calculator estimates your break-even month.
Frank prices a refinance across his lender network the same way he prices a purchase, then shows you the new payment, closing costs, break-even and lifetime interest difference side by side, including a clear warning when restarting a 30-year term would cost more over time than it saves each month.
How do I get started on a Port Orchard purchase?
Start with a short conversation or quote request, gather pay stubs, W-2s or tax returns and bank statements, and get a real pre-approval before you shop. Frank compares lenders for your scenario and sends you the options in writing.
In a market where good listings in Port Orchard and Manchester can move quickly, a solid pre-approval matters. Frank reviews your income, assets and credit, prices your scenario across 35+ wholesale lenders, and gives you a pre-approval letter sized to the price range you are comfortable with, not just the maximum.
From there, you get detailed Status Updates at every milestone: application received, disclosures sent, appraisal ordered and received, underwriting approval, clear to close and funding. If you are also looking at Bremerton or the north end of the county, the Bremerton and Kitsap County guides cover those areas. Start a quote or call Frank to talk through your timeline.
Financing a home in Kitsap County
Licensed in Washington, Oregon, and Idaho, helping homebuyers and homeowners explore financing for a wide range of loan programs and scenarios.
“I work with you to compare options from 35+ wholesale lenders competing for your loan.” Program details live on one page so they are always current; Frank walks you through the ones that fit your goals.
This page is general education, not a loan offer. Estimate only. This is not a Loan Estimate and not a commitment to lend. Your actual rate, payment and costs depend on your credit, the property and the loan program. Taxes and insurance are estimates. Program rules change; your loan officer will confirm current guidelines for your situation.
Run your own numbers
What clients say about working with Frank
“Frank and his team were responsive, professional yet friendly, and quite knowledgeable. Frank gave us options for our mortgage that we didn't know we had. Our loan process was so easy with Frank and his team!”
“Frank and his team were fabulous to work with. I recently worked with him on a transaction and he represented my buyers as their lender. He was always available for questions and kept us up to date every step of the way. His professionalism and attentiveness made the transaction seamless. Thank you Frank for all of your hard work!”
Source: Frank’s Client Reviews page on Vantage Mortgage Brokers’ website. Read all reviews.
Related guides
- Kitsap County: Puget Sound living with the Olympics out the windowGet to know Kitsap County: Naval Base Kitsap and its military community, Olympic Mountain views, the waterfront towns of Silverdale, Bremerton, Poulsbo, Port Orchard, Bainbridge Island and Kingston, ferries to Seattle, and what living here is like. Financing guidance from Frank Ellerbroek, an independent mortgage broker with deep Kitsap roots.
- Bremerton Mortgage Broker: Financing Older Homes, Condos, and Shipyard CareersFinancing a Bremerton home: shipyard and civilian Navy income, older homes and appraisal repairs, renovation loans, downtown condos near the ferry, and small multi-family properties.
- Kitsap County VA Loans: A Practical Guide for Service Members and VeteransA plain-English guide to VA home loans in Kitsap County: zero down with full entitlement, residual income, seller concessions, reusing your entitlement, 2 to 4 unit homes, and VA appraisals.
- Kitsap County First-Time Homebuyer Guide: Loan Options, Assistance, and Next StepsA first-time buyer's guide to Kitsap County: loan programs, Washington down payment assistance, what you need saved, credit basics, and the steps from pre-approval to closing.
Sources
- City of Port Orchard (opens in a new tab)
- Kitsap Transit: fast ferry and foot ferry service (opens in a new tab)
- Washington State Ferries: schedules and routes (opens in a new tab)
- NAVSEA: Puget Sound Naval Shipyard & Intermediate Maintenance Facility (opens in a new tab)
- VA.gov: VA-backed purchase loan (opens in a new tab)
- Defense Travel Management Office: Basic Allowance for Housing (opens in a new tab)
- USDA: Property eligibility map (opens in a new tab)
- Washington State Housing Finance Commission: Homebuyers (opens in a new tab)
- HUD Single Family Housing Policy Handbook 4000.1 (opens in a new tab)
- Fannie Mae Selling Guide (opens in a new tab)
- CFPB: Buying a house, step by step (opens in a new tab)