Related video
Low Down Payment Loan Options
Conventional 3% down, FHA, VA and USDA at a glance.
Watch on its own pageHow do lenders treat State of Oregon and other public employee income?
Favorably. Salaried public employment documents cleanly with pay stubs and W-2s, and lenders can usually count scheduled step increases, overtime with a history, and PERS-related income for retirees. New state hires can often qualify on an offer letter.
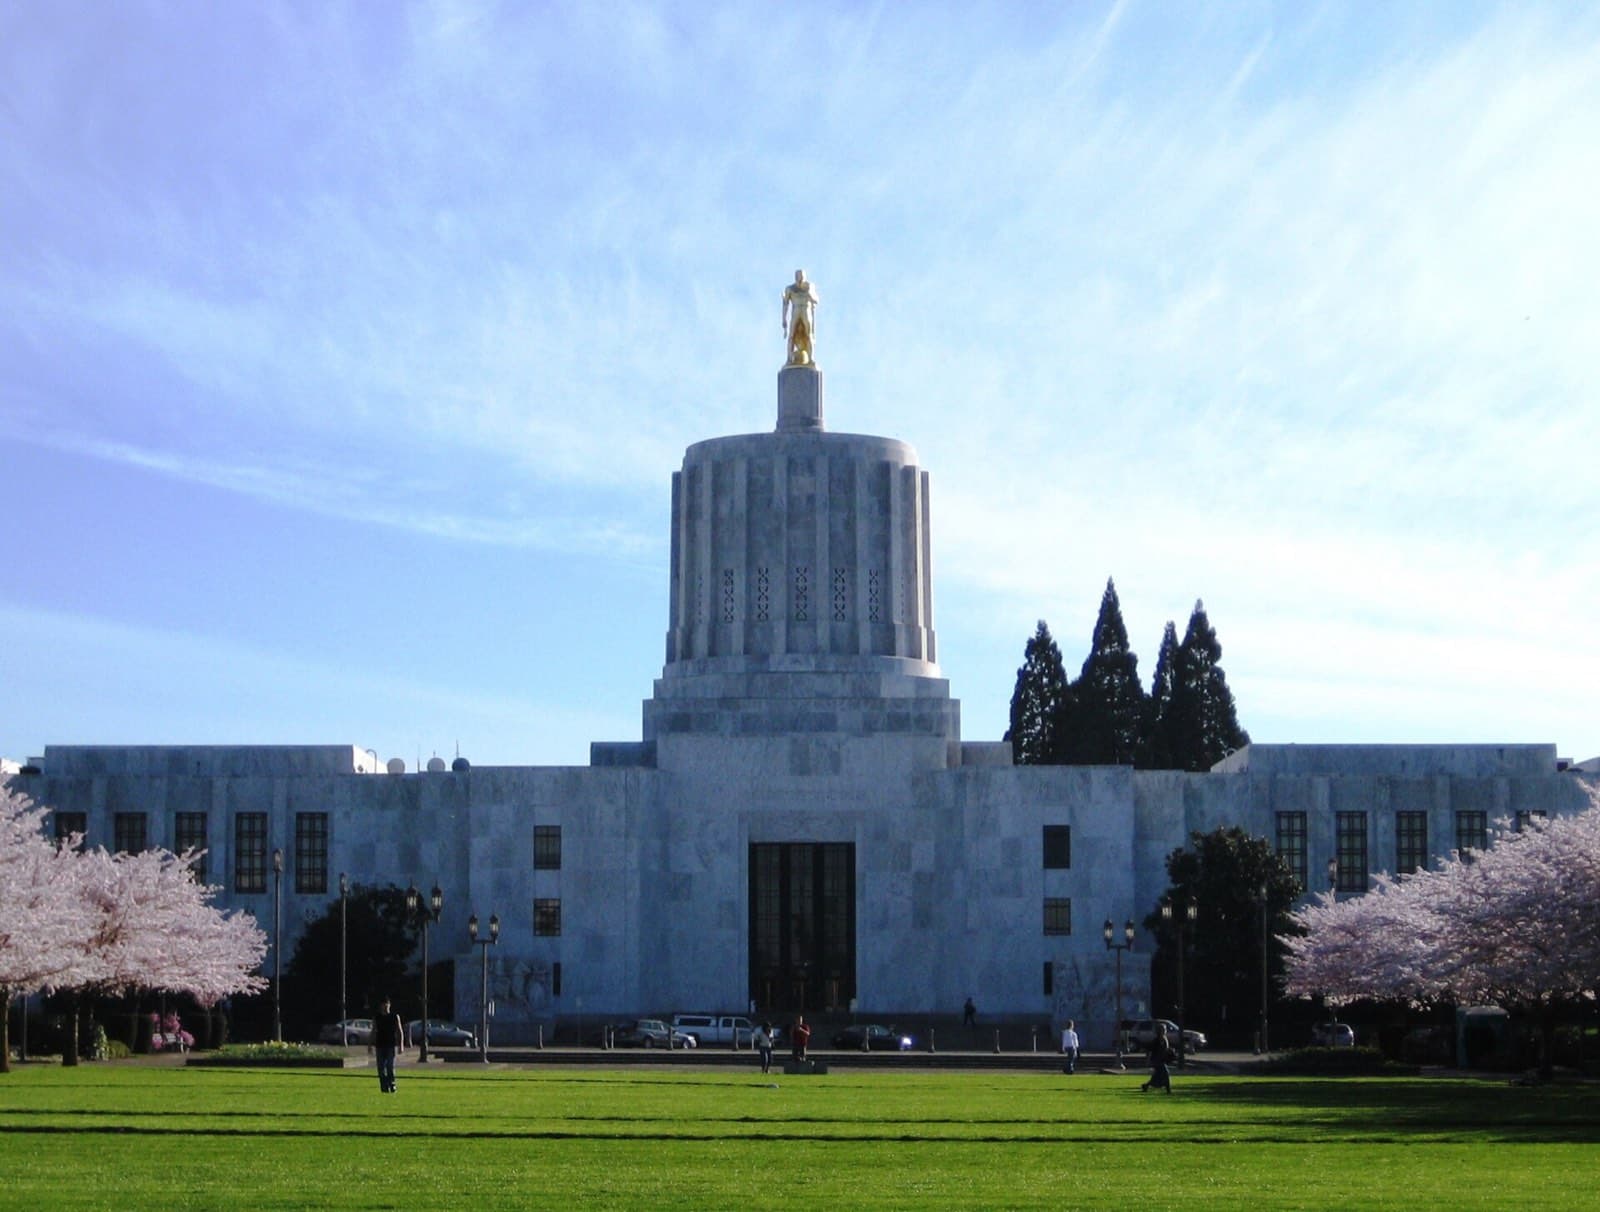
Salem's largest employers are public: state agencies downtown, Marion County, Salem-Keizer schools, Chemeketa Community College and Salem Health. Underwriters like this income because it is stable and easy to verify. A few details that come up:
- Probationary or trial-service periods are generally fine for salaried positions; lenders look at the employment being permanent in nature.
- Overtime, differentials and second jobs need a history, typically two years, to count.
- Retirees drawing PERS or other pensions document income with award letters and bank deposits, and some non-taxable income can be grossed up.
- Union and seasonal workers in agriculture and food processing can qualify with a two-year history that shows the pattern.
Frank asks for your documents once, reads them the way an underwriter will, and tells you which lenders fit before you fall in love with a house.
Can I get a USDA zero-down loan near Salem?
Inside Salem and Keizer, no; they are too large. Many addresses just outside the urban growth boundary, and towns such as Silverton, Stayton, Turner, Aumsville, Jefferson, Dallas and Independence, are USDA-eligible, subject to the household income limit for the area.
USDA guaranteed loans require no down payment and have a lower mortgage insurance cost than FHA, but two tests apply: the property must be in an eligible area on USDA's map, and household income must be under the area limit (which counts everyone in the household, not just borrowers). The guarantee fee is financed and an annual fee is included in the payment.
Marion and Polk counties are a USDA sweet spot because the eligible towns are a short commute to Salem jobs. Check the exact address on USDA's eligibility map, and run the payment calculator with USDA selected to see the fee structure. Frank's lenders include USDA specialists, and he will tell you honestly when FHA or a 3% conventional loan is the better deal despite the down payment.
What are the lowest down payment options for a first Salem home?
Conventional 3% down (HomeReady, Home Possible or standard first-time buyer programs), FHA 3.5% down, VA zero down for eligible veterans, USDA zero down on eligible addresses, and Oregon Housing and Community Services' Oregon Bond Residential Loan with a reduced rate or closing cost assistance.
With Salem prices lower than the metro, the down payment gap is smaller in dollars, and the choice between programs is mostly about mortgage insurance and credit. Conventional loans drop mortgage insurance once you reach 20% equity; FHA's insurance lasts the life of the loan at 3.5% down but is easier to qualify for with lower scores or higher debt ratios. The Oregon Bond program layers on top of any of these within income and purchase price limits and requires a homebuyer education class.
Gift funds from family are allowed on all of these programs with a gift letter and a paper trail. Frank shows you the total monthly cost of each option side by side rather than just the rate. Start with the affordability calculator.
How do Salem property taxes and the lack of a transfer tax affect my costs?
Marion County has no real estate transfer tax, and Oregon's Measure 50 limits an existing home's assessed value growth to 3% a year, so taxes on long-held homes are often lower than the price would suggest. Use the actual Marion County tax statement when estimating your payment.
Closing costs on a Salem purchase are mostly lender, title, escrow and recording fees plus prepaid taxes and insurance; there is no transfer tax line. Property tax rates vary by tax code area, with Salem's including local levies and bonds, and the assessed value does not reset when you buy. New construction in south and west Salem is assessed closer to market because new homes are an exception to the 3% cap, so compare the tax statement on a new home with that on a resale when weighing the two. Marion County's Assessor's Office posts statements online.
Is it better to rent or buy in Salem right now?
With prices below the metro and rents that have risen, buying often breaks even within a few years for someone who plans to stay, but the answer depends on your down payment, rate and how long you will keep the home. Run the numbers rather than guessing.
The rent vs. buy calculator compares cumulative rent against the net cost of owning, including taxes, insurance, maintenance and the cost of selling later. Salem's lower prices mean a smaller down payment is tied up, which narrows the opportunity-cost argument for renting. If you expect to move for a job within two years, renting usually wins and Frank will say so; if you are settling in, buying tends to come out ahead.
How does Frank work with Salem clients?
By phone, email and secure online application, with Status Updates at every milestone. Vantage's office is in Lake Oswego, under an hour north, for an in-person meeting when it helps. Banks, mortgage bankers, and credit unions offer their own loans. A mortgage broker shops the market.
Frank prices your scenario across his wholesale lenders, shows you the options side by side with the total cost, and keeps you updated from application received through disclosures, appraisal, approval, clear to close and funded. Start a quote or see every loan program available in Oregon.
Financing a home in Oregon
Licensed in Washington, Oregon, and Idaho, helping homebuyers and homeowners explore financing for a wide range of loan programs and scenarios.
“I work with you to compare options from 35+ wholesale lenders competing for your loan.” Program details live on one page so they are always current; Frank walks you through the ones that fit your goals.
This page is general education, not a loan offer. Estimate only. This is not a Loan Estimate and not a commitment to lend. Your actual rate, payment and costs depend on your credit, the property and the loan program. Taxes and insurance are estimates. Program rules change; your loan officer will confirm current guidelines for your situation.
Run your own numbers
What clients say about working with Frank
“Frank and his team were responsive, professional yet friendly, and quite knowledgeable. Frank gave us options for our mortgage that we didn't know we had. Our loan process was so easy with Frank and his team!”
“Frank and his team were fabulous to work with. I recently worked with him on a transaction and he represented my buyers as their lender. He was always available for questions and kept us up to date every step of the way. His professionalism and attentiveness made the transaction seamless. Thank you Frank for all of your hard work!”
Source: Frank’s Client Reviews page on Vantage Mortgage Brokers’ website. Read all reviews.
Related guides
- Portland Mortgage Broker: Home Loans Across the Portland MetroBuying or refinancing in Portland: how Oregon's Measure 50 keeps assessed value below market value, Portland Housing Bureau down payment assistance, no transfer tax in Multnomah County, and how an independent broker compares lenders for you.
- Hillsboro Mortgage Broker: New Construction and Silicon Forest Home LoansFinancing a home in Hillsboro: new construction and builder incentives vs. an independent broker's pricing, the Washington County transfer tax at recording, relocation buyers on new jobs, and rate buydowns paid by builders.
- Bend Mortgage Broker: Second Homes, Vacation Rentals and Central Oregon LoansFinancing in Bend and Deschutes County: second home vs. investment occupancy, short-term rental permits and DSCR loans, wildfire insurance availability, winter appraisal timing, and how an independent broker compares lenders.
Sources
- USDA: Property eligibility map (opens in a new tab)
- USDA: Single Family Housing Guaranteed income eligibility (opens in a new tab)
- USDA Rural Development: Single Family Housing Guaranteed Loan Program (opens in a new tab)
- Oregon Housing and Community Services: Homebuyer programs (Oregon Bond Residential Loan) (opens in a new tab)
- Marion County Assessor's Office (opens in a new tab)
- Oregon Department of Revenue: Maximum Assessed Value Manual (Measure 50) (opens in a new tab)
- Freddie Mac: Home Possible mortgage (opens in a new tab)
- HUD.gov: FHA loans for home buyers (opens in a new tab)
- VA.gov: VA home loans (opens in a new tab)