Buying
Weekly Rate Tracker 10/14/2026
 Frank EllerbroekMortgage Broker · NMLS #128726Vantage Mortgage Brokers · NMLS #35986Published 3 min read
Accessibility
Buying
Frank EllerbroekMortgage Broker · NMLS #128726Vantage Mortgage Brokers · NMLS #35986Published 3 min read
DATE: Wednesday, October 14th, 2026
TIME: 1:00 PM PST
STATES: IDAHO, WASHINGTON AND OREGON
CHANGE THIS WEEK: SLIGHT IMPROVEMENT (since last Wednesday)
SUGGESTION: LOCK
A Little Rate Relief—and a Reason to Think Strategically
Mortgage rates have improved modestly since last Wednesday—a welcome break after weeks of upward pressure. Still, daily swings remain common, and the latest economic data show why a sustained decline has been difficult.
Inflation remains the biggest hurdle. September’s Consumer Price Index showed prices rising 3.7% over the past year, up from 3.4% in August. Core inflation, which excludes food and energy, rose 0.3% for the month, exceeding expectations of 0.2%. Even a small surprise can move mortgage pricing as investors reassess the outlook for interest rates.
The bond market reacted quickly. The 10-year Treasury yield climbed above 5.3% following the report before retreating later in the day—a good example of how quickly conditions can change. Mortgage rates respond to the broader bond market, rather than moving directly with the Federal Reserve’s rate decisions.
Meanwhile, oil prices above $100 a barrel and continued tensions involving Iran are adding inflation pressure. Traders have increased their expectations for another Fed rate hike, although that outcome remains uncertain.
What does this mean for homebuyers? Higher borrowing costs continue to challenge affordability, but slower demand can give buyers more time to compare homes and negotiate. Depending on the property and local competition, that could mean a better purchase price, seller help with closing costs or more room to negotiate repairs.
My approach: look at the whole picture. Compare lenders, loan costs and seller-credit options, and make sure the full payment fits comfortably. Any future refinance should be an opportunity, rather than something your budget depends on.
My website’s Live Rates feature is also an easy place to start—no personal information required.
Interest Rate Pricing Options*
(rates subject to change)
MONTHLY PAYMENTS: This reflects Principal and Interest (P&I) on Conventional and also including PMI on FHA. Taxes and insurance not included, but need to be factored in housing payments and budget as these can vary by property. A VMG Mortgage Broker can run an analysis anytime by request.
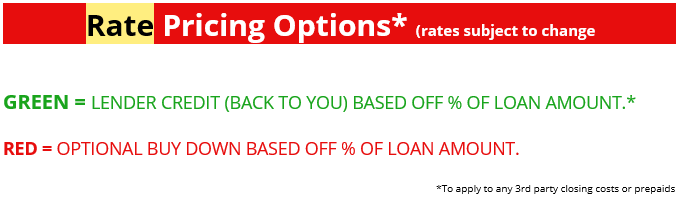
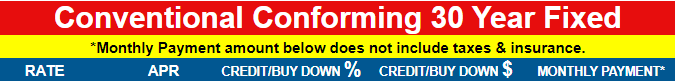
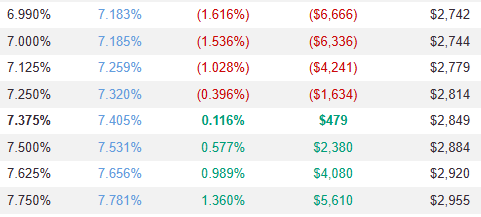
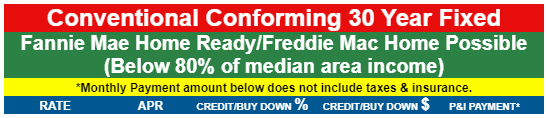
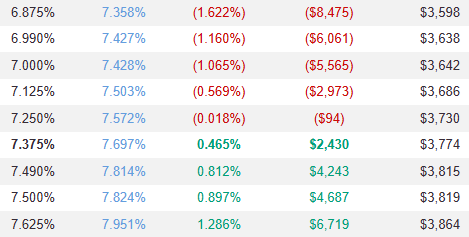
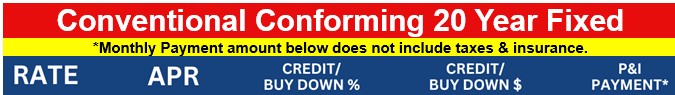
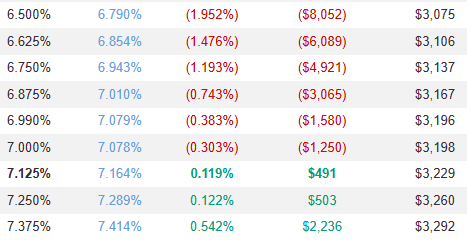
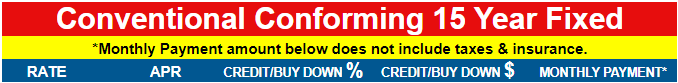
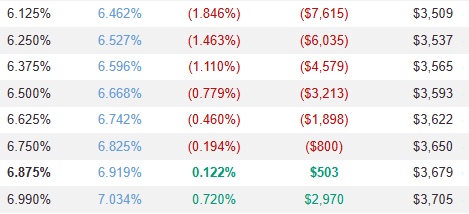
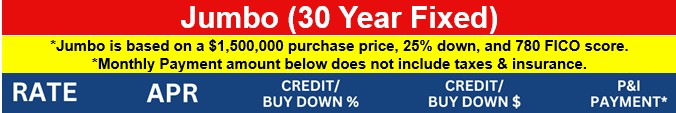
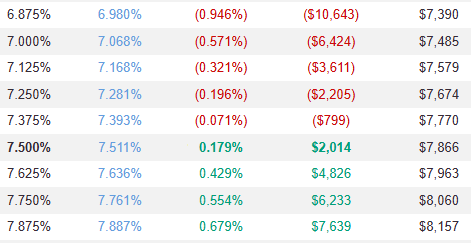
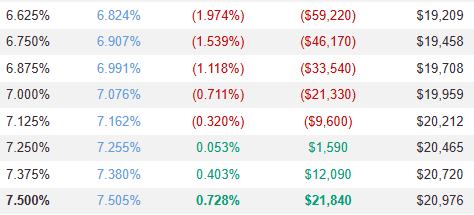
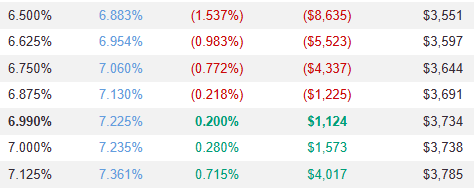
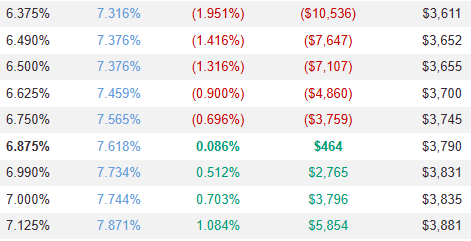
*Rates are subject to change. Conforming conventional interest rate samples based on a $550,000 purchase price, $412,500 loan amount, 25% down, 740 FICO score, with impounds on a 30-day rate lock period and $1150 underwriting fee if not covered by lender rebates. FHA is based on a $550,000 purchase price, $530,750 base loan amount and a 3.5% down payment, but other same variables. This pricing engine reflects the most favorable results after comparing our network of wholesale lending partners. This pricing engine does not include any other applicable 3rd party title and escrow charges, appraisal, credit report, or prepaid tax and insurance reserves. The displayed annual percentage rates (APRs) include total points and additional prepaid finance charges but do not include other closing costs. Loan pricing may only be locked through a VMB home loan consultant to be effective after a formal loan application. Rates will depend in part on your unique credit history and transaction characteristics. Monthly payments include principal, interest, and PMI if applicable, but do not taxes and insurance. This is not a formal Loan Estimate (LE). A Loan Estimate is provided and can be requested pursuant to Federal regulations and with a formal loan application. This information does not constitute a loan commitment or approval.
Tell Frank what you’re trying to do. He’ll shop 35+ wholesale lenders and show you the options side by side.
This article is general information, not a Loan Estimate, a commitment to lend or financial advice for your specific situation. Rates and programs change; confirm the details with Frank before you act. Frank Ellerbroek, NMLS #128726, Vantage Mortgage Brokers, NMLS #35986.
VA loans3 min read
VA bonus entitlement, also called second-tier or extended entitlement, may allow eligible veterans to buy a new primary residence while keeping an existing VA-financed home. Learn how remaining entitlement is calculated, when a down payment may be required, and how benefits such as no monthly mortgage insurance can help. Frank Ellerbroek with Vantage Mortgage Brokers helps veterans in Washington,